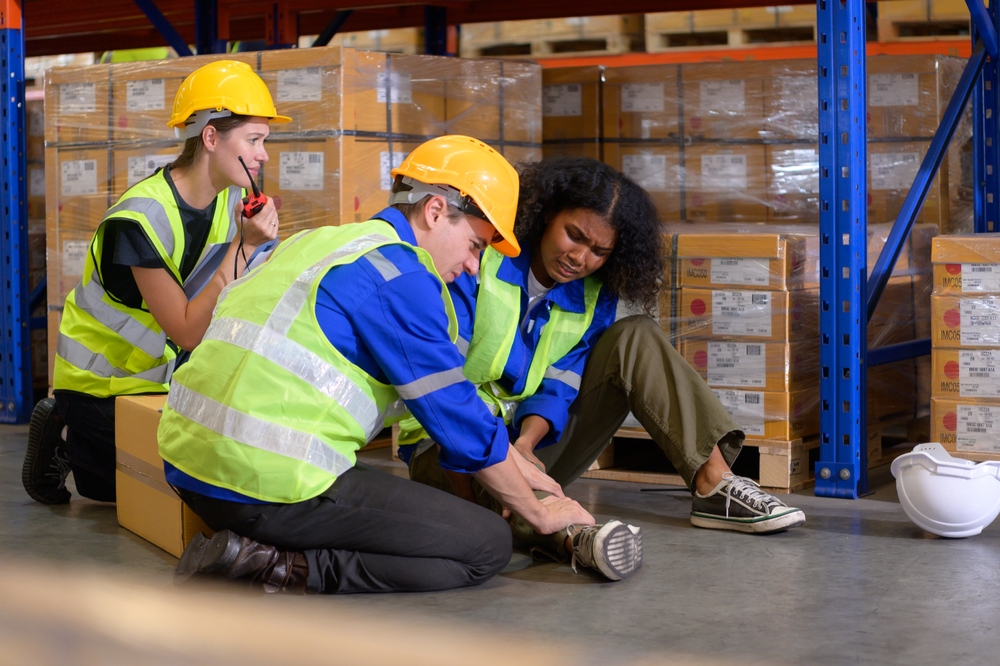
Employers often ask why insurance companies pay the wrong employee claims.
The answer may be that it’s cost effective. Why incur court costs when you know the claimant will accept less than the cost of mounting a defence? The other answer is that sometimes they have no choice, especially when health and safety planning has been botched or ignored.
Consider the questions
There are three questions that accident and injury lawyers will ask all claimants:
- Did your employer have a health and safety policy?
- When did you last receive a copy?
- Have you signed your training record?
If the answer to all 3 is “no” the employer is in breach of a central plank of health and safety legislation. A defence is difficult to mount. Companies that specialise in mounting “no win – no fee” claims realise it’s prudent to keep claims under certain thresholds because they know it is not economical for insurers to incur legal costs attempting to defend. And claims will be paid when they shouldn’t be.
Some insurers seek to recover defence costs from businesses that have shown a flagrant disregard for health & safety. If they cannot repay the insurer the rest of us receive inflated premiums.
The last time I looked, up to 40% of UK employers’ liability premiums were spent defending claims. Premiums would increase further if insurers started fighting losing battles.
So how do we avoid funding these sometimes ill gotten gains? A great way to reduce insurance premiums now and in the future is to embrace health and safety planning. It’s not as complicated as it’s made out to be, common sense is the order of the day. If businesses had effective, up to date health and safety policies, these claims could be declined meaning reduced costs for insurers and lower premiums for all – except those sectors that collectively ignore such plans.
Top Tip:
If you have a governing body or trade association let them know they can help you cut costs by improving standards in your sector. I’m happy to help you work out how to tackle your liabilities.
P.S. Have a peek at some of the myths the HSE have exploded.
See our top tips page for simple ways to help yourself today.
